

The decisions being made by a small number of companies are increasingly driving global economic performance. After each quarter’s earnings releases, we share this update to reveal what’s driving their performance, and how they are allocating capital.
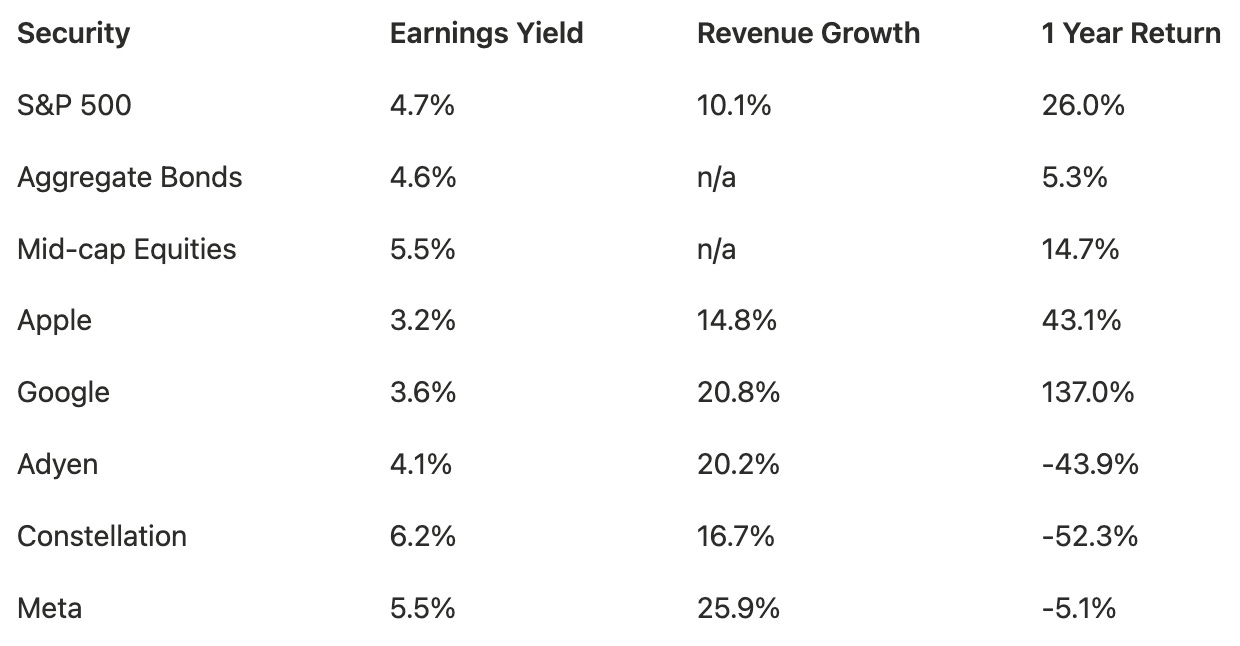
Share prices have recently been rising faster than earnings. Google, in particular, is one stock we are re-evaluating. The combination of a peak valuation multiple, along with orders from customers with unprofitable business models, is driving our caution.
Market Updates
The capex number got bigger again. Google led another upward revision in datacenter capex: total 2026 spending estimates for market leaders now stand at $725B, up from $640B last quarter. Google also committed to spending even more in 2027.
Claude’s chatbot is winning the enterprise. Launches of Claude Code, Claude Cowork, and Claude for Small Business solidified this position. ChatGPT still owns consumer usage.
Memory chip shortage. The shift from inference chatbots to agentic chatbots drove new demands for memory, and along with it, extreme share price jumps for Micron and Samsung. Historically, spikes like this have rarely held.
Private capital. Blackstone, KKR, and Apollo all faced higher redemptions in their private credit vehicles. In their earnings calls, they failed to provide evidence that private credit conditions are in fact stable, helping justify our exit from this sector.
Largest Individual Holdings
Google: Backlog orders for Google’s cloud computing jumped to $460 billion, up from $155 billion six months ago. Private AI companies are making aggressive commitments for Google’s services. Those companies will have to continue to raise funding to deliver on those commitments.
S&P 500: Since the start of 2026, Google has been the biggest contributor to the index while Microsoft has been the biggest laggard.
Apple: Continued resurgence in Chinese demand is driving strong results for the iPhone.
Adyen: Made their first large acquisition: $750M for Talon.One, a loyalty company that will enable upsell opportunities at the point-of-sale.
Constellation: Robust financial performance continues. Acquisitions are accelerating, and the new CEO is taking a more transparent approach to investor relations.
Valuation Table
Footnotes
Earnings Yield is estimated 1-year forward earnings per share divided by current stock price
Revenue Growth based on 2026 analyst consensus estimates
1 Year Return is the change in stock price over the last 12 months
We remain focused on businesses with durable economics and disciplined capital allocation. Our aim is to adjust exposure when valuations dislocate from fundamentals.
Upholdings